How to Open a Trust Account for Property Management
Learn how to open a trust account for property management: choosing a bank, required documents, and state rules to check before you set one up.
Summary: Opening a trust account for property management means choosing a bank that supports dedicated trust or sole-purpose accounts, gathering your business license and management agreements, and setting up records that keep each owner’s funds separate from your own. Most STR property managers also need a way to separate funds by owner or property within that account, not just from their operating account. Below is the step-by-step process, what to check with your bank and your state before you open one, and where a purpose-built system like Clearing changes the setup.
Why Property Managers Need a Trust Account
If you collect rent, deposits, or booking revenue on behalf of property owners, that money isn’t yours. It belongs to the owner until it’s distributed, minus your commission. A trust account keeps those funds legally and financially separate from your business’s operating account, so a bookkeeping error, an audit, or a dispute with one owner never puts another owner’s money at risk.
Opening the account is the mechanical, one-time setup. Trust accounting is the ongoing discipline of tracking every dollar that moves through it, by owner, by property, and by transaction type.
Step by Step: Opening a Trust Account
1. Choose a bank that supports trust or sole-purpose accounts. Not every bank offers this account type, and terms vary. Look for a bank that explicitly supports trust, escrow, or sole-purpose business accounts, ask whether they’ve worked with property managers before, and compare fees, minimum balance requirements, and interest terms. Check out our roundup of the best bank accounts for short-term rentals that breaks down features, fees, and tradeoffs across the major choices.
2. Gather your documentation. Banks typically ask for your business license, your EIN, and a statement of purpose describing what the account will hold. If you’re managing on behalf of owners under signed agreements, bring copies of those management agreements. Some banks also want a sample of the trust language you plan to use in owner contracts.
3. Decide how you’ll separate funds within the account. A single trust account holding every owner’s money isn’t enough on its own. You need a system, whether that’s a spreadsheet, your bookkeeping software, or dedicated sub-ledgers, for tracking exactly how much of the account balance belongs to each owner at any given time. This is the step most new property managers underestimate, and it’s where commingling risk actually starts.
4. Set up your record-keeping before you take your first deposit. Open the account, then build your tracking system before any money moves through it. Retrofitting records onto an account that already has six months of transactions is far harder than starting clean.
5. Confirm your state’s specific requirements. This is the step to slow down on.
What to Verify With Your State
Trust accounting requirements vary by state, and they’re not uniform. Some states require a dedicated trust account for any funds held on behalf of a client, some don’t require a dedicated account at all as long as funds are properly tracked, and some states require separate accounts per owner rather than one shared trust account with internal tracking.
We haven’t independently verified the current requirement for every state, so treat this as a starting point, not a final answer: check with your state’s real estate commission or property management licensing authority, or with an attorney familiar with trust accounting rules in your state, before finalizing your account structure. If you manage properties across multiple states, this is worth confirming separately for each one.
What Documentation Do You Need to Open a Trust Account?
Banks treat trust and sole-purpose accounts as higher-scrutiny products, so expect more paperwork than opening a standard business checking account. Common requirements include:
- Proof of identity. You will need to provide a form of photo ID and proof of your address.
- Business license. Proof your property management business is licensed to operate in your state.
- EIN. Your business’s tax ID, separate from any personal Social Security number.
- Statement of purpose. A short description of what the account will hold and how it will be used, usually a bank form rather than something you draft from scratch.
- Management agreements. Signed agreements with the owners whose funds you’ll be holding, showing your authority to collect and disburse on their behalf.
- Banking resolutions or formation documents. If you operate as an LLC or corporation, banks typically want articles of incorporation or a banking resolution naming who can act on the account.
- Account title. Most banks require the account name to clearly show the funds belong to your clients, not your business, something like “[Your Company Name] Client Trust Account” rather than just your business name.
- Anti-Money Laundering check. Most jurisdictions require you to provide an AML check in order to open a trust account.
Requirements vary by bank and by state, so confirm the exact list with your chosen bank before your appointment.
What to Include in Your Management Agreement
Your trust account is only as reliable as the agreement that governs it. This isn’t a formal legal trust document with a grantor and trustee, it’s the management agreement between you and each property owner, and it should spell out exactly how their funds will be handled.
Details of the arrangement. Name the parties involved, the property or properties covered, the term of the agreement, and exactly which funds fall under it, rent, security deposits, cleaning fees, reserves, or any combination.
Rules for managing funds. Specify your commission structure and when it’s deducted, how often owners receive statements and distributions, how disputes or discrepancies get resolved, and what happens to the arrangement if either party wants to end it.
Getting these terms in writing before you open the account, rather than after your first deposit, is what makes the account defensible if an owner ever questions a balance.
Types of Trust Accounts You Can Use
The right structure depends on your bank, your state’s rules, and how many owners you manage funds for. A few common options:
- Sole-purpose or dedicated trust account. A single account used only for client funds, with internal sub-ledger tracking to show each owner’s share of the balance. This is the most common setup for property managers with more than a handful of clients.
- High-yield savings account. A high-yield savings account can be an alternative option, offering competitive interest rates on the balance of your account. Unlike a sole purpose account, a high-yield savings account typically does not require a statement of purpose. This type of account can be suitable if you plan to hold onto the funds for an extended period rather than making frequent withdrawals or deposits.
- Certificate of Deposit (CD) account. A CD account is another option that may provide higher interest rates compared to regular savings accounts. It offers guaranteed returns on investments, but typically involves longer terms (such as 1-5 years or more) and early withdrawals may incur substantial penalties. Consider the term and liquidity needs of your rental funds before choosing a CD account.
Remember, it’s essential to consult with your financial institution to understand the specific types of trust accounts they offer, their requirements, and any associated fees or restrictions. This will help you choose the most suitable account for managing your rental income and property funds effectively.
Common Setup Mistakes
A few mistakes show up often enough to call out directly.
Opening the account and figuring out tracking later. As noted above, this creates a backlog of transactions to reconstruct, and it’s the single biggest source of commingling risk in the first few months.
Treating the trust account like a second operating account. Trust funds shouldn’t be used to cover business expenses, even temporarily, even when you’re confident you’ll pay it back and rebalance the account later.
Assuming one account structure fits every state you operate in. A structure that satisfies your home state’s requirements may not satisfy another state where you manage properties.
No audit trail for transfers between the trust account and your operating account. Every commission transfer or fee withdrawal should be documented at the time it happens, not reconstructed at month-end.
A Software Alternative to Opening Multiple Accounts
Some property managers, especially as they scale past a handful of owners, open a separate bank account per owner to keep funds cleanly separated. That solves the separation problem, but it multiplies the operational overhead: more accounts to open, more statements to reconcile, more places for an error to hide.
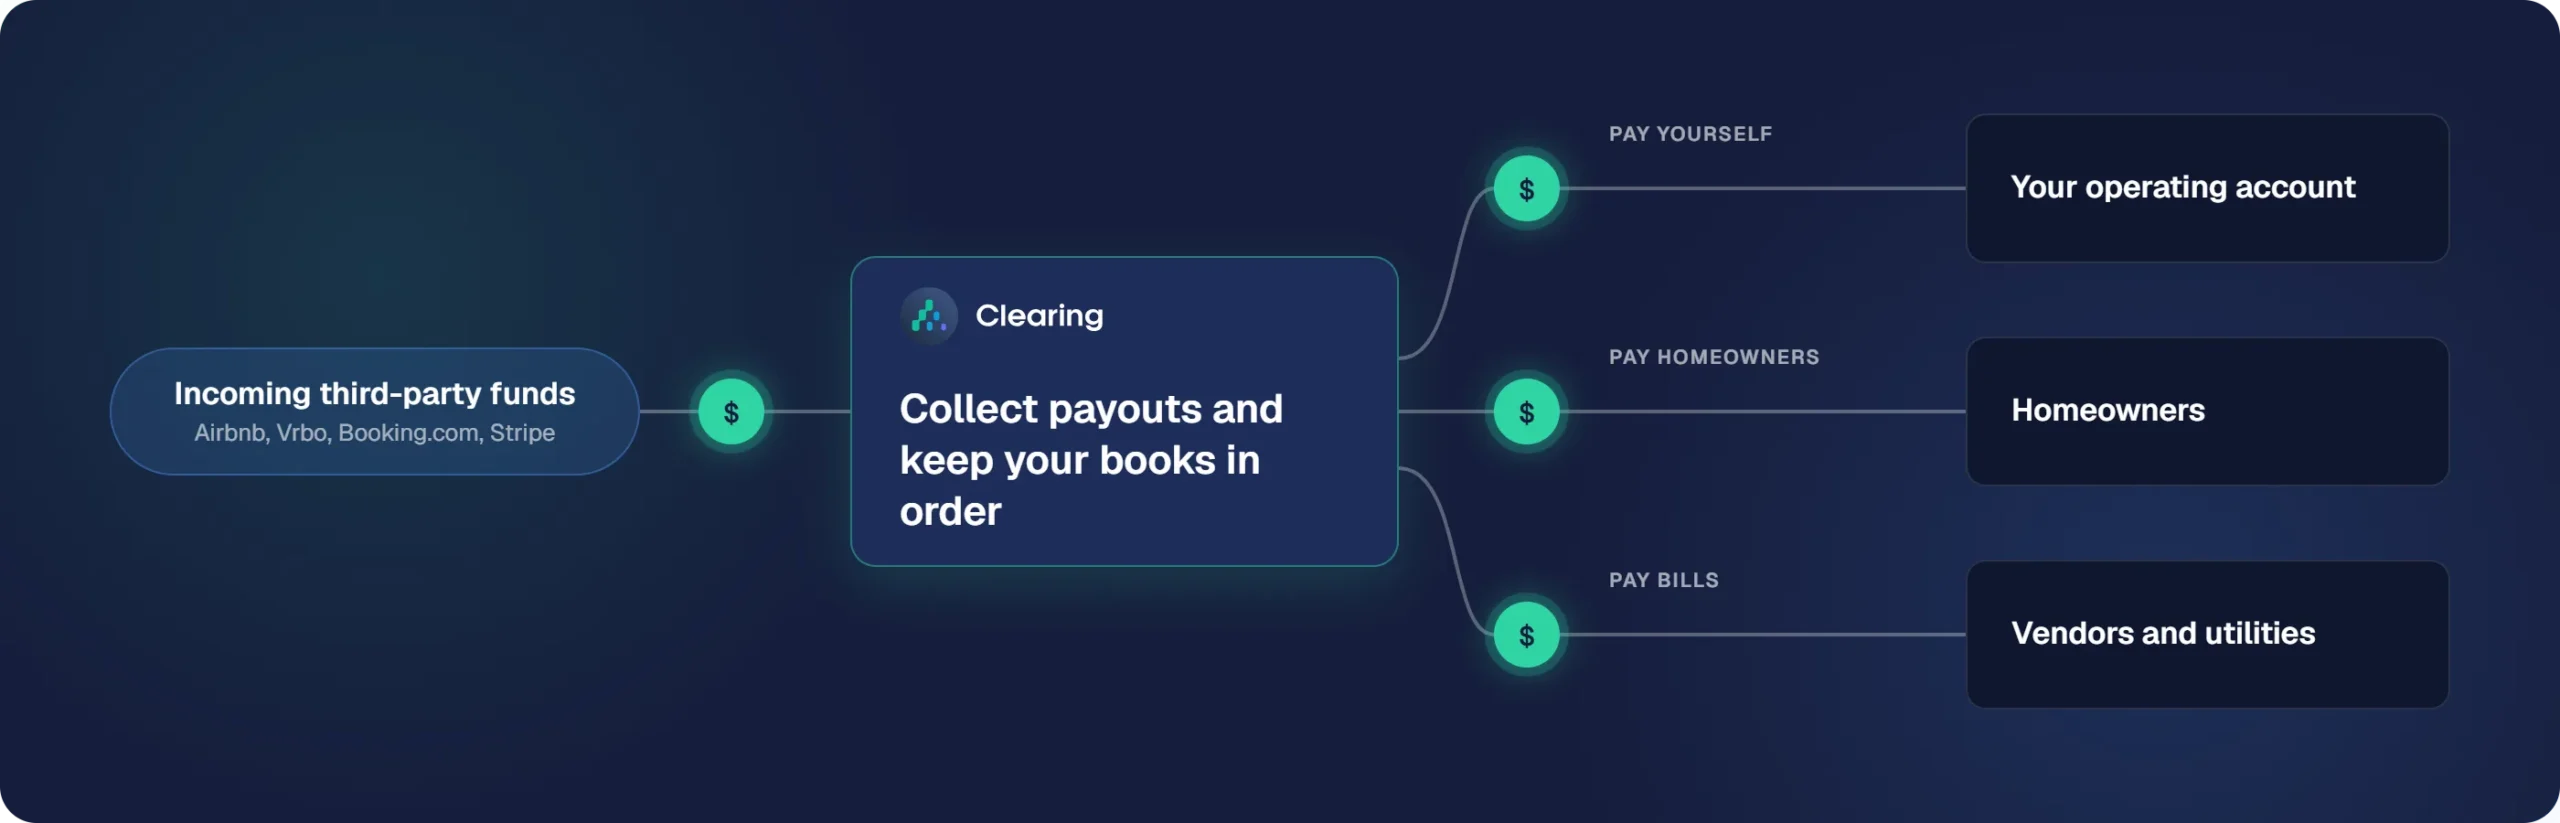
Clearing takes a different approach. Instead of opening a new bank account per owner, Clearing’s trust accounting features let you separate funds by owner, property, or category, like commission and tax payments, within a single account, so records stay organized without separate account paperwork for every new client.
This is the same underlying discipline covered in our trust accounting guide: separate the money first, then build a system that makes that separation provable at any point in time, not just at year-end.
FAQ
Do I need a separate trust account for each property owner I work with? Not always. Many states allow one trust account with internal sub-ledger tracking per owner, though some states do require fully separate accounts per owner. Confirm your state’s specific rule before deciding.
What documents does a bank typically require to open a trust account? Most banks ask for a business license, an EIN, a statement of purpose for the account, and copies of your management agreements with property owners.
Can a trust account earn interest? It depends on the account type and your bank. Some trust accounts are interest-bearing, others aren’t, and some states have rules about what happens to interest earned on client funds. Check with your bank and your state’s regulations.
What’s the difference between a trust account and my business operating account? Your operating account holds money that belongs to your business, like commissions you’ve earned. A trust account holds money that belongs to owners until it’s distributed. The two should never mix.


Clearing is a Financial Technology Company, not a bank.